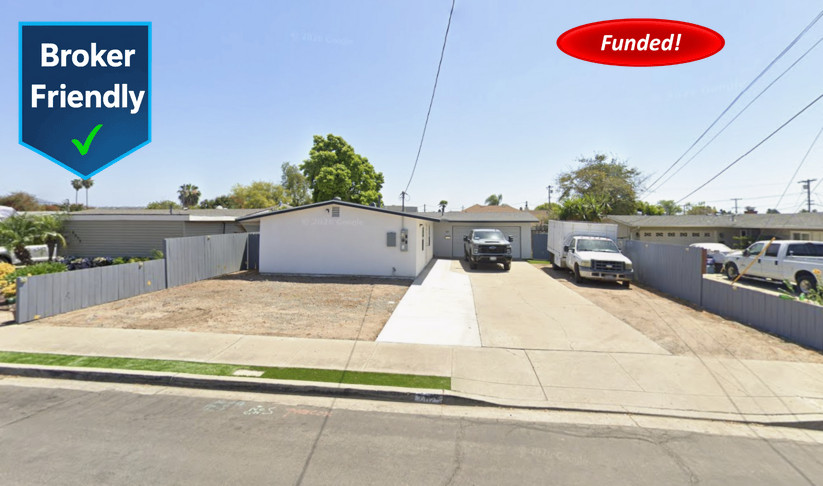
Mortgage Vintage successfully funded a $276,000 second trust deed ADU construction loan in La Mesa, California, secured by an owner-occupied single-family residence in San Diego County. This La Mesa ADU loan supported the construction of a fully permitted, two-story accessory dwelling unit at the rear of the subject property, with all loan proceeds held in funds control and disbursed in accordance with an approved construction schedule.
Why This La Mesa ADU Loan Stood Out
- The combined loan-to-value ratio came in at a conservative 65.00% CLTV, with a net CLTV of just 44.60%, based on a $1,400,000 after-repair appraised value.
- The borrower demonstrated strong creditworthiness with a 761 FICO score and a clean mortgage payment history.
- Approved architectural plans and a building permit were already in hand at the time of funding, reducing entitlement risk substantially.
- An independent construction budget review confirmed the $276,000 budget was adequate to complete the full scope of work.
- The borrower contributed more than $35,000 in cash to close, demonstrating meaningful equity participation.
- Six months of guaranteed interest and three months of prepaid interest provided investors with a defined income floor from day one.
- A clearly defined exit strategy through post-construction refinancing provided a credible repayment path.
Property Description
The subject property was a single-family residence situated on a 9,583-square-foot lot in La Mesa, San Diego County, California. The existing home contained approximately 1,267 square feet of living space with three bedrooms and two bathrooms. The proposed ADU was designed as a detached, two-story structure of approximately 1,196 square feet, inclusive of a 143-square-foot entry patio, adding three bedrooms and three bathrooms to the overall property. Upon completion, the property was projected to generate approximately $2,700 per month in additional rental income from the new unit. The after-repair appraised value of the combined improvements was established at $1,400,000. Investors seeking similar opportunities can explore Mortgage Vintage’s ADU construction loan program for details on underwriting criteria and available structures.
Investment Summary
Mortgage Vintage originated this transaction as a 2nd trust deed position construction loan carrying a 12.50% note rate and a 24-month term. The existing first mortgage balance of $634,000 combined with the new $276,000 second trust deed produced a total combined loan balance of $910,000 against the $1,400,000 appraised after-repair value. All construction funds were held in a funds control account, with disbursements released in stages tied to verified construction milestones. The loan featured six months of guaranteed interest and three months of prepaid interest, offering participating investors a predictable, secured yield. This transaction was made available to accredited investors through the CrowdTrustDeed platform, where fractional trust deed investments are presented with full underwriting transparency. The borrower’s exit strategy centered on refinancing the property into permanent financing upon completion of the ADU, using the increased property value and rental income to qualify for a takeout loan that would retire the construction debt.
Financial Details
| Field | Value |
|---|---|
| Loan Amount | $276,000 |
| Note Rate | 12.50% |
| Lien Position | 2nd Trust Deed |
| Loan Term | 24 Months |
| CLTV | 65.00% |
| Net CLTV | 44.60% |
| Appraised After-Repair Value | $1,400,000 |
| Existing First Mortgage | $634,000 |
| Combined Loan Balance | $910,000 |
| Guaranteed Interest | 6 Months |
| Prepaid Interest | 3 Months |
| Minimum Investment | $55,200 |
| Funds Control | $276,000 (Full Loan Amount) |
| Borrower FICO Score | 761 |
| Exit Strategy | Refinance Upon ADU Completion |
Property Highlights
| Field | Value |
|---|---|
| Property Type | Single-Family Residence (SFR) |
| Occupancy | Owner-Occupied |
| City | La Mesa, CA |
| County | San Diego |
| Lot Size | 9,583 sq. ft. |
| Existing Home Size | 1,267 sq. ft. |
| Existing Bedrooms / Bathrooms | 3 Bed / 2 Bath |
| ADU Size | 1,196 sq. ft. (+ 143 sq. ft. Entry Patio) |
| ADU Bedrooms / Bathrooms | 3 Bed / 3 Bath |
| ADU Type | Detached, Two-Story |
| Projected ADU Rental Income | $2,700 / Month |
| Construction Timeline (Estimated) | Approximately 6 Months |
| Permit Status at Funding | Approved Plans and Building Permit in Hand |
Frequently Asked Questions
Why would a lender use funds control on an ADU construction loan?
Funds control is a risk management tool used by lenders like Mortgage Vintage to ensure construction loan proceeds are released only as specific, verified milestones are completed. Rather than disbursing the full loan amount at closing, an independent third-party funds control agent holds the construction budget and releases draws upon inspection and approval of completed work. This protects both the lender and the investors by keeping the project on track and ensuring loan proceeds are applied directly to the approved scope of construction.
What makes ADU construction loans different from traditional home improvement loans?
ADU construction loans are purpose-built to finance the full cost of adding a new, self-contained dwelling unit to an existing residential property. Unlike home equity lines of credit or conventional renovation loans, ADU construction loans are structured around a detailed construction budget, a draw schedule tied to project milestones, and an after-repair valuation that accounts for the value added by the new unit. Because they are business-purpose loans secured by real property, they are typically originated by private or hard money lenders rather than conventional banks, and they carry terms tailored to the construction timeline rather than a long-term amortization schedule.
How does the San Diego County rental market support ADU investment strategies?
San Diego County, including communities like La Mesa, has consistently ranked among California’s tightest rental markets, with strong demand driven by population density, limited housing supply, and proximity to major employment centers. For property owners, adding a permitted ADU can generate meaningful monthly rental income while simultaneously increasing overall property value. These dynamics make ADU construction a compelling investment strategy in the region, as the rental income supports debt service during the loan period and strengthens the borrower’s refinancing position upon project completion.
Mortgage Vintage, Inc. is a California DRE-licensed hard money lender and trust deed investment company with deep experience structuring and funding complex construction and ADU loan transactions across California’s diverse real estate markets. Our team applies rigorous underwriting standards, independent budget reviews, and disciplined funds control protocols to every transaction, delivering secured, income-producing trust deed investments to accredited investors with transparency and expertise.