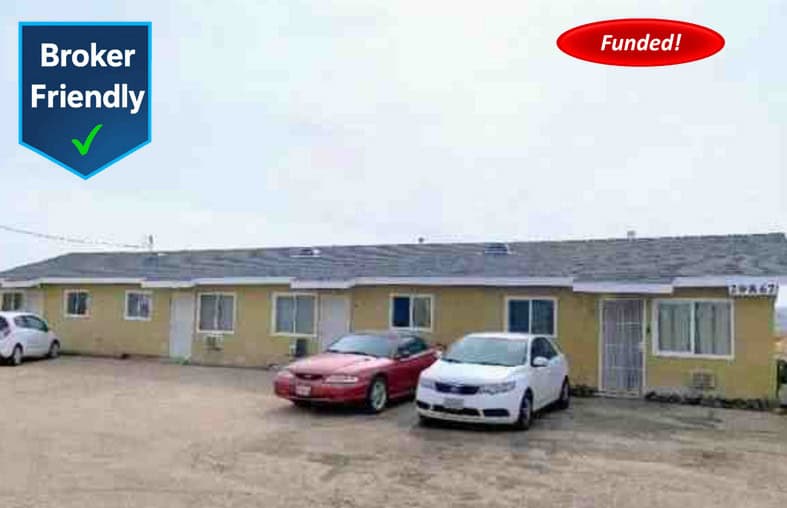
Mortgage Vintage successfully funded a $374,000 first trust deed purchase loan secured by a 7-unit residential income property in Barstow, California. The borrower, who carried a 733 FICO score, acquired the property under a contract price of $535,000 — a figure that aligned precisely with the appraiser’s concluded as-is market value as of September 2, 2026. This multifamily hard money loan program transaction was structured as a 12-month term with 6 months of guaranteed interest, providing trust deed investors with a reliable and defined income stream from day one. The Barstow multifamily loan was originated, underwritten, and funded by Mortgage Vintage in its capacity as a California hard money lender, with the opportunity made available to accredited investors through the CrowdTrustDeed platform.
Why This Barstow Multifamily Loan Stood Out
- 733 FICO borrower demonstrating strong creditworthiness for a non-owner-occupied investment acquisition
- 69.91% LTV based on a $374,000 loan against a $535,000 as-is appraised value, creating approximately $161,000 in protective equity
- First lien position providing senior security interest in the collateral
- 6 months guaranteed interest offering investors a defined minimum return regardless of payoff timing
- 7-unit income-producing property with a potential gross income of approximately $82,800 annually at stabilized occupancy
- Approximately 70,000 SF of excess land on the 161,000 SF site, identified by the appraiser as having potential for additional units or ADU development
- Appraised value confirmed at contract price using the sales comparison approach with income and cost approach support
- Borrower brought additional cash reserves of approximately $60,000 earmarked for property improvements and repairs
Property Description
The subject property was a 7-unit residential income property located in Barstow, San Bernardino County, California, built in 1955. The improvements consisted of wood-frame construction with a stucco exterior and composition-shingle roofing. The portfolio of units included six one-bedroom/one-bath apartments and a single-family residence functioning as a two-bedroom/one-bath home, totaling approximately 4,056 square feet of net rentable area spread across three buildings. The property offered surface parking for seven or more vehicles and was reported in average overall condition. The appraisal noted deferred maintenance items, including two units without ranges and certain wall air-conditioning units that appeared non-operational — factors that the borrower planned to address using available capital reserves. The property sat on an unusually large site of approximately 161,000 square feet, with the appraiser identifying roughly 70,000 square feet as excess land with potential for further development. At the time of origination, the property was approximately 43% occupied, with four of the seven units vacant, presenting a clear value-add lease-up opportunity for the acquiring investor.
Investment Summary
This completed Barstow multifamily loan was structured at a 69.91% loan-to-value ratio, based on the $374,000 loan amount and the $535,000 as-is appraised value. The protective equity position at origination stood at approximately $161,000. The loan carried an interest rate of 10.50% with a 12-month term and 6 months of guaranteed interest, giving trust deed investors clarity on their minimum yield. The minimum investment for this offering was $37,400. The income analysis, supported by market rents and a 6% stabilized vacancy and collection-loss allowance, produced an estimated net operating income of approximately $45,452 and an income approach value of approximately $505,000 — providing additional underwriting support beneath the sales comparison conclusion of $535,000. The borrower committed cash to close and retained reserves of approximately $60,000 designated for unit improvements and deferred maintenance, reducing the risk profile associated with the property’s below-stabilized occupancy at origination.
Financial Details
| Field | Value |
|---|---|
| Loan Amount | $374,000 |
| Interest Rate | 10.50% |
| Lien Position | 1st Trust Deed |
| Loan-to-Value (LTV) | 69.91% |
| Appraised As-Is Value | $535,000 |
| Protective Equity | ~$161,000 |
| Loan Term | 12 Months |
| Guaranteed Interest | 6 Months |
| Minimum Investment | $37,400 |
| Deal Type | Purchase |
| Occupancy | Non-Owner Occupied |
| Borrower FICO | 733 |
| Estimated NOI (Stabilized) | ~$45,452 |
| Potential Gross Income | ~$82,800 Annually |
Property Highlights
| Field | Value |
|---|---|
| Property Type | Multi-Family Residential Income (7 Units) |
| Location | Barstow, CA (San Bernardino County) |
| Year Built | 1955 |
| Number of Buildings | 3 |
| Unit Mix | Six 1-Bed/1-Bath Units + One 2-Bed/1-Bath SFR |
| Net Rentable Area | ~4,056 SF |
| Site Size | ~161,000 SF |
| Excess Land (Est.) | ~70,000 SF |
| Construction | Wood Frame, Stucco Exterior, Composition Shingle Roof |
| Parking | Surface Parking, 7+ Vehicles |
| Occupancy at Origination | ~43% (3 of 7 Units Occupied) |
| Stabilized Vacancy Allowance | 6% |
| Development Potential | Possible Additional Units or ADUs on Excess Land |
Frequently Asked Questions
Why would an investor choose a hard money loan for a multi-family purchase in a market like Barstow, California?
Hard money loans are particularly well-suited for value-add multi-family acquisitions where conventional financing is difficult to obtain due to low occupancy or deferred maintenance. In this transaction, the property was approximately 43% occupied at the time of purchase, making conventional bank financing unlikely. A hard money lender like Mortgage Vintage was able to underwrite the loan based on the as-is appraised value, the borrower’s credit profile, and the income potential of the asset — allowing the acquisition to close efficiently while the borrower executed a lease-up and improvement plan.
How does guaranteed interest protect trust deed investors in a short-term loan like this?
Guaranteed interest — in this case, 6 months — means that trust deed investors receive a contractually defined minimum amount of interest income regardless of when the borrower repays the loan. If the borrower pays off the loan early, say in month three, investors still receive the equivalent of 6 months of interest. This provision is especially valuable in short-term bridge and purchase loans, where early payoff is common, and it ensures investors are fairly compensated for deploying capital into the deal.
What role does excess land play in the valuation and risk assessment of a multi-family investment property?
Excess land refers to a portion of the site that is beyond what is needed to support the existing improvements and could theoretically be developed or sold separately. In this transaction, the appraiser identified approximately 70,000 square feet of excess land on the 161,000 square-foot site, assigning it a value of approximately $22,000. While excess land can add incremental value and future development optionality — such as additional rental units or ADUs — lenders like Mortgage Vintage typically underwrite conservatively and do not rely on speculative development value when establishing the loan amount. The primary collateral value was supported by the income-producing improvements and confirmed market comparable sales.
Mortgage Vintage, Inc. is a California Department of Real Estate-licensed hard money lender and trust deed investment company with extensive experience structuring, underwriting, and funding income-property loans across California’s diverse real estate markets. With a disciplined focus on collateral quality, borrower creditworthiness, and investor protection, Mortgage Vintage has established a track record of successfully closing complex multi-family and investment property transactions that conventional lenders cannot accommodate.