Loan Purpose
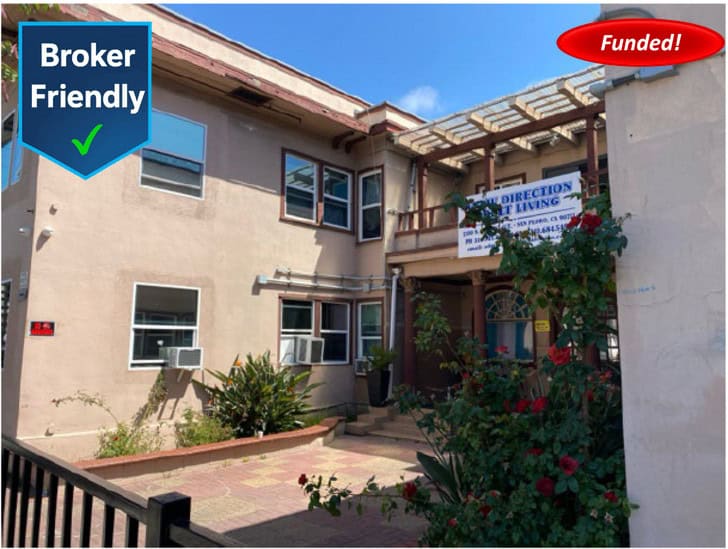
Mortgage Vintage successfully funded a $735,000 second trust deed secured by a licensed 72-bed Adult Residential Facility located at 2300 South Pacific Avenue in San Pedro, California. This was a business-purpose rate and term refinance with no cash out to the borrower. Loan proceeds were used to pay off an existing maturing first trust deed, retire a PACE loan obligation, satisfy taxes and other outstanding liens, and cover normal closing costs. The refinance was structured to clean up a layered debt stack and provide the borrower with a bridge period to establish sufficient operating and tax-return history needed to pursue an SBA or conventional permanent refinance. Mortgage Vintage originated a $735,000 2nd Trust Deed at 14.50% interest sitting behind a new $3,800,000 first trust deed, bringing total combined debt to $4,535,000 against a CBRE-appraised real estate value of $7,070,000. This San Pedro commercial loan carried a 12-month term with 6 months of guaranteed interest and a 3-month prepayment premium, with a minimum investment of $36,750. Investors who participated through the CrowdTrustDeed platform earned a 14.50% annualized return on a collateral-backed trust deed position.
Why This San Pedro Commercial Loan Stood Out
- Licensed 72-bed Adult Residential Facility with institutional-quality CBRE appraisal supporting a $7,070,000 real estate value
- Approximately 64.1% combined LTV based solely on real estate value, with an additional $2.42 million in business and FF&E value providing further enterprise cushion
- Strong 1.60x DSCR on combined new debt based on independently underwritten stabilized NOI of approximately $902,000
- Approximately 95% stabilized occupancy, with Q1 2026 averaging approximately 97.2%
- Revenue meaningfully supported by government-backed programs through county mental health and managed care partnerships, providing recurring and relatively stable income
- New financing structure reduced estimated monthly debt service from approximately $52,400 to approximately $46,400, improving cash-flow coverage
- Experienced operator with a track record dating to 2016 and more than $1.396 million invested in capital improvements to the subject property
- Multi-facility operator with a separately acquired 94-bed facility and more than $10 million in non-repayable grant capital awarded across the portfolio
- No cash out to the borrower — a pure debt restructuring with a clear SBA or conventional refinance exit strategy
Property Description
The collateral securing this loan was a licensed 72-bed Adult Residential Facility totaling approximately 20,423 square feet situated on approximately 0.45 acres in San Pedro, California. The operator had owned and managed the facility since 2016 and invested approximately $1.396 million in capital improvements over that period, including the roof, windows, flooring, electrical systems, kitchen, water heaters, and bathrooms. At the time of the independent appraisal, occupancy was reported at 94.4%, and the facility had averaged approximately 97.2% occupancy during Q1 2026. The independent appraiser underwrote stabilized occupancy at approximately 95%. A meaningful portion of residents were supported through county mental health and managed care programs, providing a recurring revenue base with government-program backing. The property was valued at $7,070,000 for real estate alone, with a total going-concern enterprise value of approximately $9,490,000 when business value and FF&E were included. Mortgage Vintage relied exclusively on the real estate value for underwriting purposes. This type of specialized commercial asset is well suited for Mortgage Vintage’s commercial hard money loan program, which is designed to serve operators and investors in non-standard property types that require lender expertise and flexibility.
Investment Summary
The capital structure placed Mortgage Vintage’s $735,000 second trust deed behind a $3,800,000 first trust deed, for total combined debt of $4,535,000. Against the CBRE real estate value of $7,070,000, the resulting combined LTV was approximately 64.1%. The stabilized NOI of approximately $902,000, as independently underwritten by the appraiser, supported annual combined debt service of approximately $556,750, producing an estimated 1.60x to 1.62x DSCR — meaningfully above the 1.25x threshold commonly required by institutional commercial lenders. The loan carried a 14.50% annual investor return, a 12-month term, 6 months of guaranteed interest, and a 3-month prepayment provision. The borrower’s prior credit challenges stemmed from COVID-era operating disruptions and were followed by a successful recovery, with occupancy and cash flow both returning to healthy levels by the time Mortgage Vintage underwrote the transaction. The borrower was on a structured payment plan for remaining SBA-related obligations and had maintained the current private mortgage without default since restructuring. The deal was presented and fully funded through the trust deed investment marketplace, with a minimum investment of $36,750 per participating investor.
Financial Details
| Field | Value |
|---|---|
| Loan Amount | $735,000 |
| Investor Rate | 14.50% per annum |
| Lien Position | 2nd Trust Deed |
| Loan Type | Rate and Term Refinance |
| Loan Purpose | Business-Purpose Bridge Refinance |
| Loan Term | 12 Months |
| Guaranteed Interest | 6 Months |
| Prepayment Interest | 3 Months |
| Minimum Investment | $36,750 |
| 1st Trust Deed Balance | $3,800,000 |
| Total Combined Debt | $4,535,000 |
| Combined LTV (Real Estate Only) | 64.14% |
| Stabilized NOI | ~$902,000 (independently appraised) |
| DSCR | ~1.60x on combined new debt |
| Cash Out to Borrower | None |
| Exit Strategy | SBA or Conventional Refinance |
Property Highlights
| Field | Value |
|---|---|
| Property Type | Licensed Adult Residential Facility (Commercial) |
| Location | San Pedro, California |
| Licensed Capacity | 72 Beds |
| Building Size | ~20,423 Square Feet |
| Lot Size | ~0.45 Acres |
| CBRE Real Estate Value | $7,070,000 |
| Total Enterprise Value (Going Concern) | $9,490,000 |
| Stabilized Occupancy (Appraiser) | ~95% |
| Actual Occupancy (Q1 2026 Avg.) | ~97.2% |
| Capital Improvements by Operator | ~$1,396,000 since 2016 |
| Revenue Support | Government-backed county mental health and managed care programs |
| Operator Tenure | Since 2016 |
Frequently Asked Questions
What makes a licensed Adult Residential Facility a suitable commercial hard money loan collateral?
Licensed Adult Residential Facilities can be strong collateral for commercial hard money loans because they combine real property value with an operating business supported by recurring, often government-backed revenue streams. When independently appraised at full going-concern value — including business value and FF&E — the total enterprise value can significantly exceed the underlying real estate alone. In this transaction, the independently appraised real estate value of $7,070,000 provided a meaningful equity cushion at approximately 64% combined LTV, while stabilized occupancy near 95% and a DSCR above 1.60x demonstrated the property’s ability to comfortably service the debt. Hard money lenders like Mortgage Vintage are able to underwrite these specialized assets by focusing on collateral quality and cash-flow coverage rather than requiring the seasoned conventional loan history that traditional lenders typically demand.
Why would a borrower choose a second trust deed refinance rather than a single first trust deed loan?
A layered capital structure — combining a first trust deed with a smaller second trust deed — is sometimes the most practical solution when a borrower needs more total financing than a single lender is willing to provide at the desired rate, or when the first trust deed lender has already committed at a specific loan amount. In this case, the first trust deed covered the bulk of the refinance need, and Mortgage Vintage’s $735,000 second trust deed filled the remaining gap to fully retire the existing debt, the PACE obligation, and other outstanding liens. This structure allowed the borrower to accomplish a complete, clean refinance without any cash out, while giving the Mortgage Vintage investor position a defined lien behind a well-capitalized first, all secured against a property with substantial equity above the combined debt load.
How does DSCR factor into underwriting a commercial hard money loan in California?
Debt Service Coverage Ratio, or DSCR, measures how many dollars of net operating income a property generates for every dollar of mortgage debt service. A DSCR above 1.0x means the property earns more than enough to cover its loan payments. In California commercial hard money lending, a DSCR of 1.25x or higher is generally viewed as the threshold for adequate coverage, and senior housing or residential care lenders often require even more. In this San Pedro transaction, the independently appraised stabilized NOI of approximately $902,000 supported a combined DSCR of approximately 1.60x to 1.62x on the new debt structure — well above institutional benchmarks. Importantly, the new financing also reduced the borrower’s monthly debt service compared to the prior arrangement, further strengthening ongoing coverage. For Mortgage Vintage, DSCR analysis is a key underwriting input on all income-producing commercial loan transactions.
Mortgage Vintage, Inc. is a California Department of Real Estate-licensed hard money lender and trust deed investment company with extensive experience originating, underwriting, and servicing commercial trust deed loans across Southern California and beyond. Our team draws on deep expertise in specialty property types, income-producing collateral analysis, and layered capital structures to deliver disciplined, collateral-focused lending solutions for borrowers and competitive yield opportunities for investors.